After a hurricane or major storm, one of the most important questions in a Florida property insurance claim is this: was the damage caused by wind or by flood?
The answer matters because wind and flood damage are typically covered under different policies. A disagreement over the cause of loss can significantly affect whether your claim is paid.
Understanding how wind versus flood damage is evaluated can help you navigate this common dispute.
This distinction comes up constantly in hurricane and tropical storm damage claims, where wind and flood damage often occur together.
How Standard Florida Homeowners Policies Work
Most Florida homeowners insurance policies cover wind damage.
This includes damage caused by hurricane force winds, torn shingles, broken windows, and wind driven rain that enters through openings created by the storm.
However, standard homeowners policies generally exclude flood damage. Flood damage is usually defined as rising water that covers normally dry land and enters the home from the ground up.
Flood coverage is typically purchased separately, often through a federal flood insurance program or a private flood insurer.
Why Wind Versus Flood Becomes a Dispute
During hurricanes, wind and water often occur at the same time.
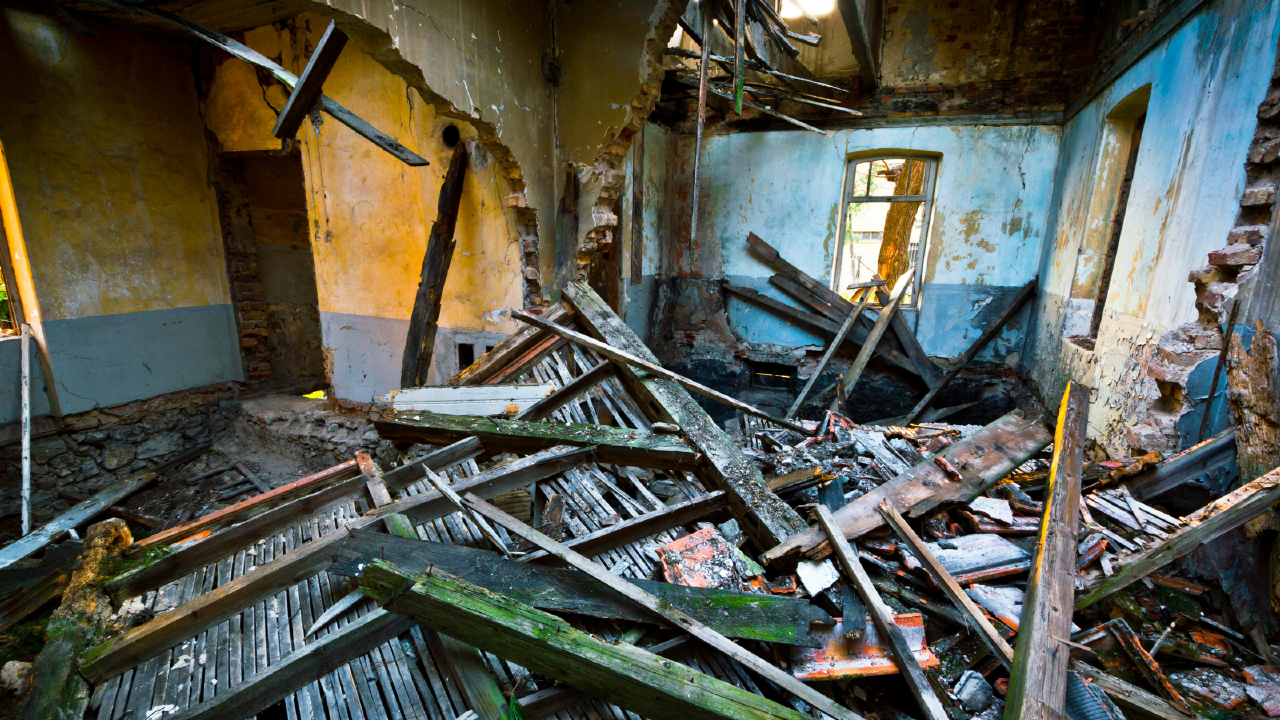
High winds can damage roofs and walls, while storm surge or rising water may enter the property from below. When both forces are present, determining which one caused specific damage can be complex.
Insurance companies may argue that certain interior damage resulted from flood rather than wind driven rain. If flood is determined to be the cause, the homeowners policy may not respond.
Homeowners often disagree with that conclusion, especially if roof or structural damage from wind is visible.
The Direction of Water Matters
One key distinction insurers evaluate is the direction from which water entered the property.
Water that enters from above, through a storm created opening in the roof or walls, is often categorized as wind driven rain and may be covered under a homeowners policy.
Water that rises from the ground and enters through doors, baseboards, or foundation openings is typically classified as flood damage.
In many cases, damage patterns and physical evidence determine how the loss is categorized.
Concurrent Causes and Complex Claims
Some claims involve both wind and flood damage.
In those situations, insurers may attempt to allocate portions of the damage between covered wind and excluded flood. This can lead to partial payments or disputed scope decisions.
Engineering reports and causation analysis often play a significant role in these cases.
If the insurer attributes most of the damage to flood, the homeowners policy may pay little or nothing, leaving the flood policy as the primary source of coverage.
Why Proper Documentation Is Critical
If your Florida property sustained hurricane damage, thorough documentation can make a difference in a wind versus flood dispute.
Photographs taken immediately after the storm, videos, eyewitness accounts, and contractor evaluations can help establish how and where water entered the property.
The timing of visible damage and the presence of roof or structural openings may also be important factors.
When to Seek a Review
If your Florida insurance claim was denied or limited because the insurer determined the damage was caused by flood rather than wind, it may be helpful to review the policy language and the inspection findings carefully.
A Florida property insurance attorney can evaluate whether the insurer’s causation analysis appears consistent with the available evidence and the terms of the policy.
If you would like to discuss a wind versus flood dispute related to your hurricane claim, you may request a consultation to review your documentation and options.